Sales-type
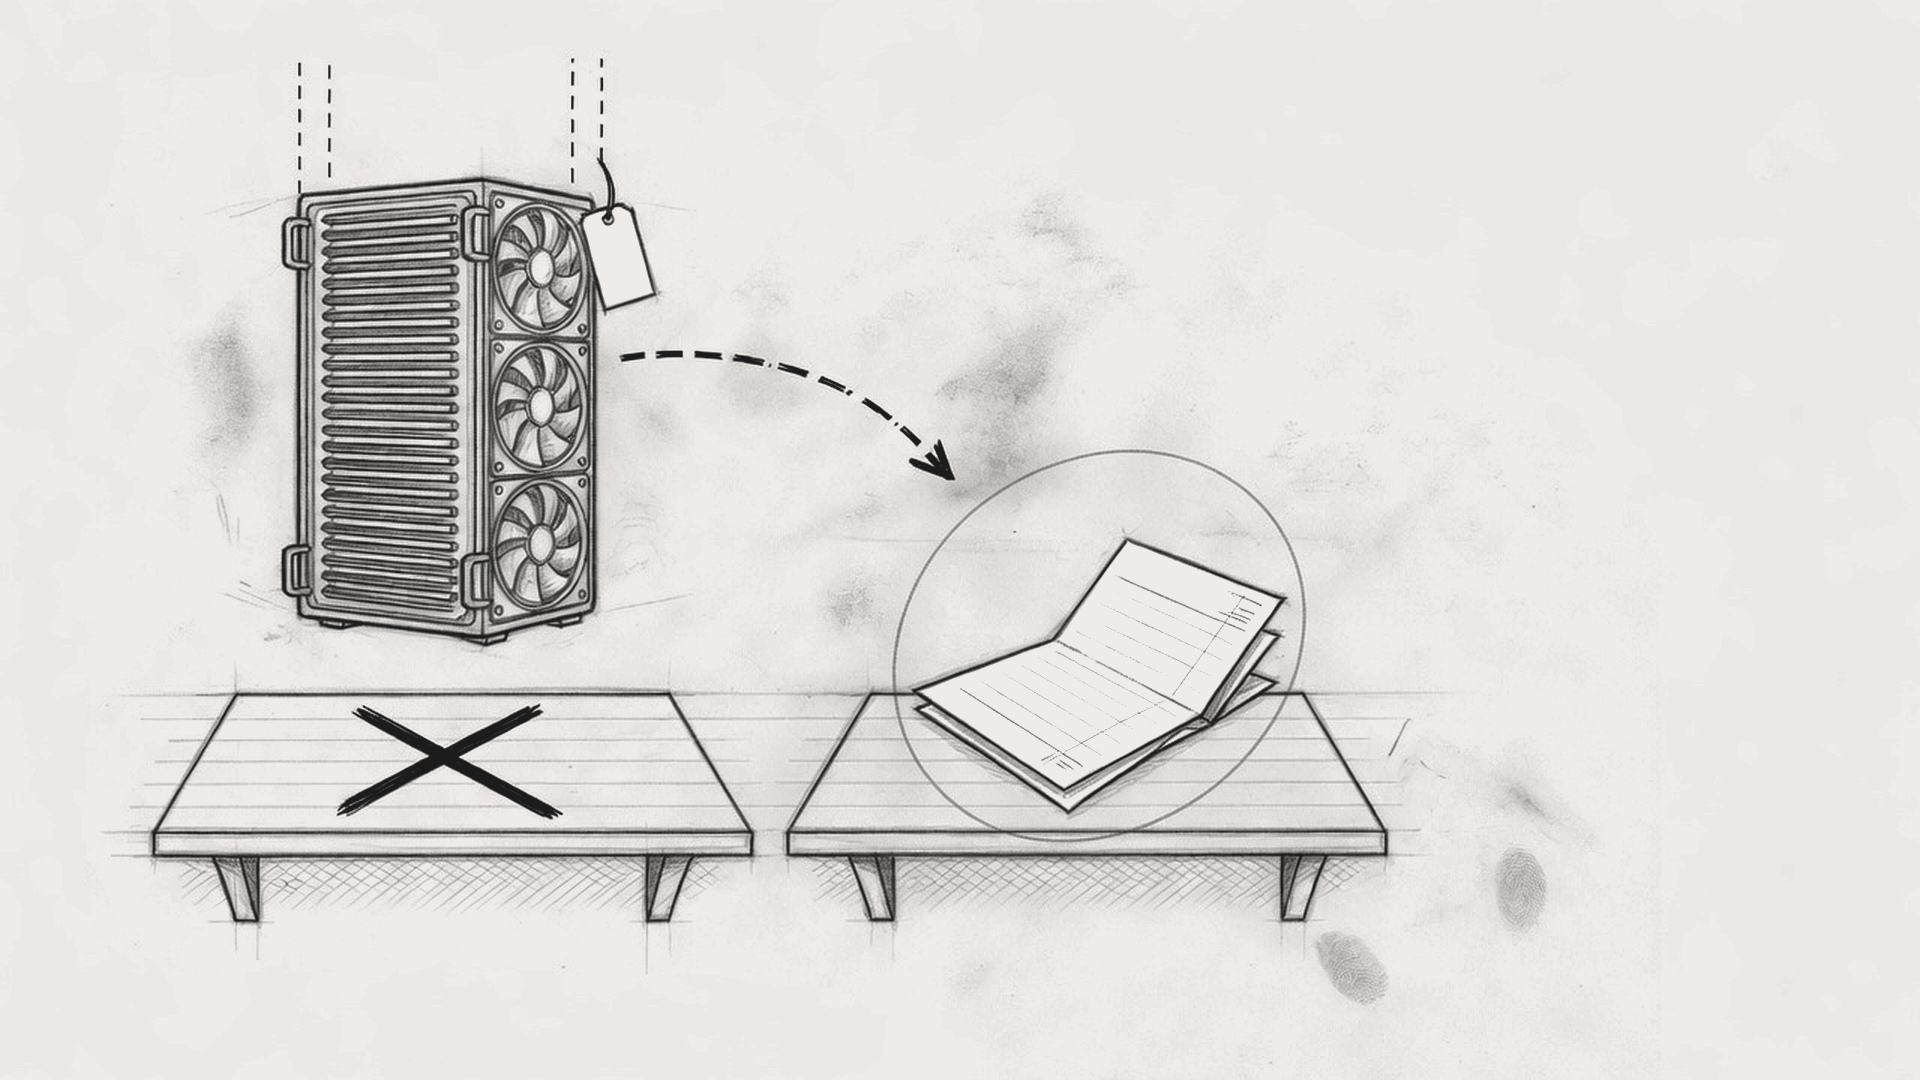
PPE leaves. NIL stays. Day-one revenue can equal cost. Then interest. Do not annualize.
28 September 2026
F.F Research · AI · 28 September 2026
At commencement, a sales-type GPU lessor takes the server off the books and leaves a net investment. BIRD has done that in a 10-Q. ALP has said it in a press release.
Article architecture · 1–5
Chapter 01
Who books an identified NVIDIA GPU server as a sales-type or finance lease.
Chapter 1 · Object
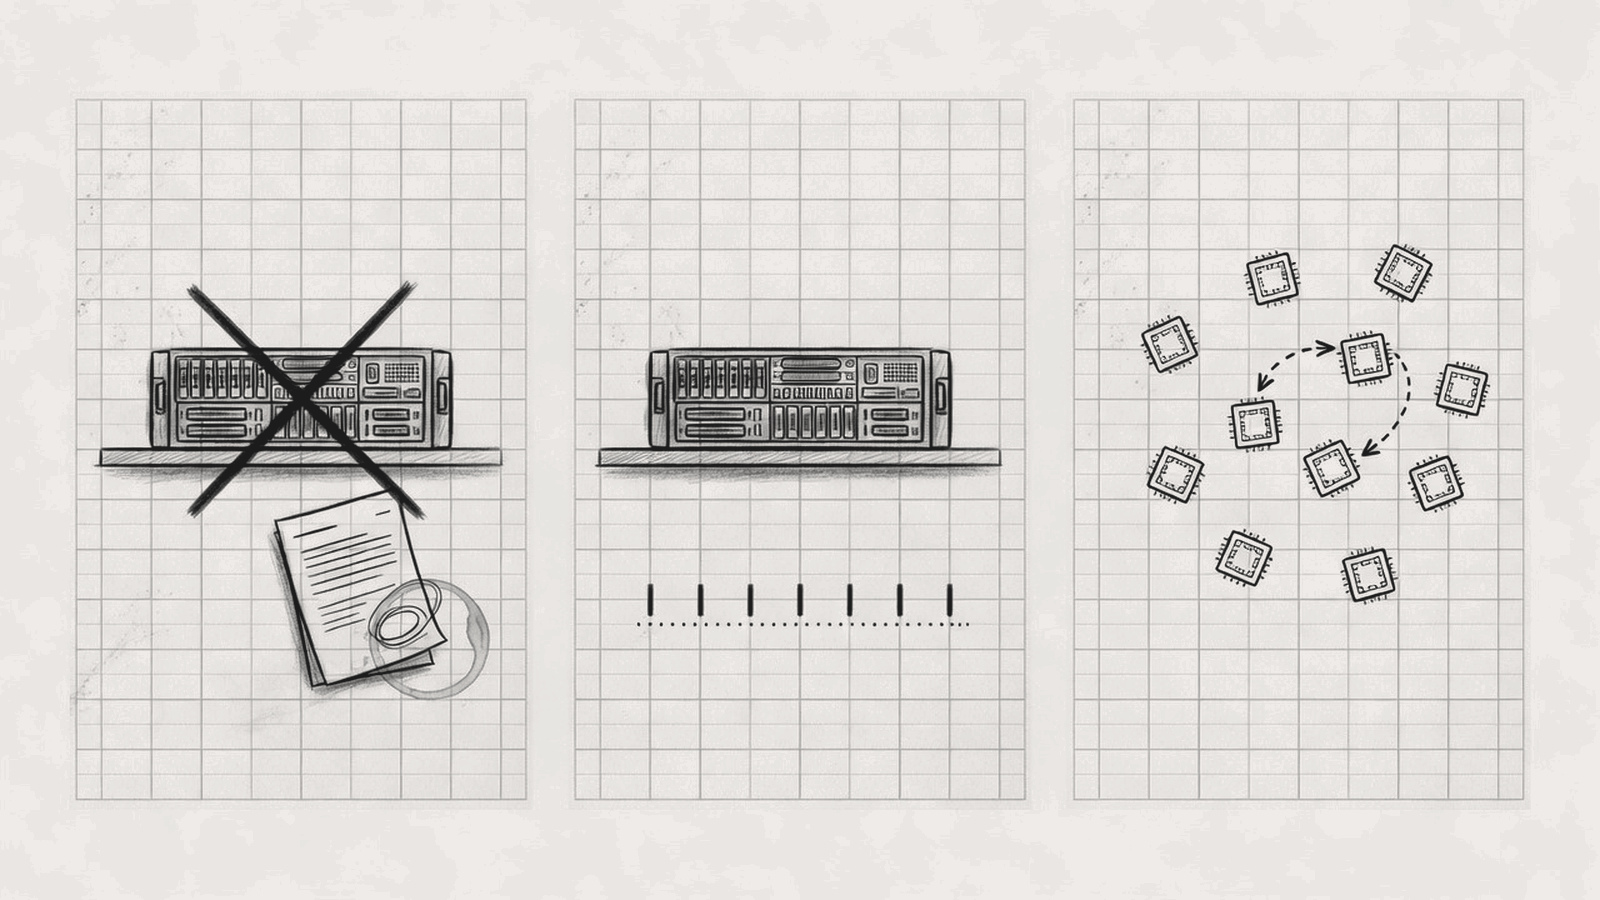
Sales-type pulls a financed sale to day one. Operating spreads rent across the term. Neither is a 606 cloud.
BIRD, formerly Allbirds, is the clean owned-asset sample. ALP, formerly Portage / AlphaTON, is the narrative neighbor: Buzz lease-in / lease-out, classification in a monthly PR.
Chapter 1 · Findings
BIRD card count is unfiled. ALP’s audited FY2026 revenue is $97k and excludes ALPHA-01.
Chapter 02
A dedicated GPU contract enters 842 or 606, then operating or sales-type.
Chapter 2 · 2.1 Three books
PPE leaves. NIL stays. Day-one revenue can equal cost. Then interest. Do not annualize.
GPU stays in PPE and depreciates. Straight-line lease revenue. Rent can be a run-rate.
No identified asset, or a substitution right remains. Deferred revenue and RPO. Not rent.
BIRD and BRUN are both lessors. Comparing their ARR sideways lies. Residual on a sales-type goes into the NIL; on an operating lease it stays with the lessor.
Chapter 2 · 2.2 Commencement · Q2'26 10-Q
Cash out to PPE. Purchase of PPE $2.758M.
PPE moves to NIL. Revenue $2.758M equals cost. Gross profit ~0.
Cash splits. Principal reduces the NIL. The rest is interest.
NIL $0.515M + $2.149M = $2.664M. Unearned interest $0.832M.
Continuing GPU PPE is gone. The $2.758M is the pulse, not a quarterly run-rate. SG&A can be an order of magnitude larger than the interest that follows.
Chapter 2 · 2.3 Same desk
Machine is off the lessor’s PPE. Prepay often sits in the NIL. Lie: annualize day-one revenue.
Machine stays on the lessor’s PPE. Lie: treat TCV as RPO.
Machine usually stays with the operator. Lie: call a dedicated cluster 842.
Chapter 03
A footwear shell that bought Blackwell and booked one sales-type lease.
Chapter 3 · 3.1 The dates
$50M secured revolver. Repaid when the shoes close.
Signed near $39.0M. Escrow $3.0M.
Blackwell and QumulusAI. First notes $3.25M.
Opened with a cap of $50M.
Formation in 2015, the 2021 IPO, and the footwear revenue years sit behind this line.
Chapter 3 · 3.1 The dates
Additional notes, $5.0M. Issued face is then $8.25M.
Cash about $40.7M. Second Avenue repaid, about $19.7M.
ATM cap about $98.1M. Smartbird. Facility to $100M.
Nadia Carlsten becomes CEO. Joe Vernachio resigns.
The 20 April 8-K summarizes the April cluster. The footwear close and the GPU lease are different checks.
Chapter 3 · 3.1 Management
Facility investors also have a 24-month ≥55% co-invest and a COO appointment right. The dilution slope can beat the operating-proof slope. That is the base and bear case, not “is there a GPU.”
Chapter 3 · 3.2 Where the business is
Divested 9 June. Gain about $21.6M. Discontinued.
One NewBird → QumulusAI sales-type. A miniature lessor.
Stockholder-letter vision. No cloud revenue line. No owned hall.
Cash ~$37.4M. Undrawn $91.75M is an option. Capacity ≠ cash.
Smartbird holds the card. The QumulusAI subsidiary is the lessee and, on the company’s telling, the operator.
Chapter 3 · 3.2 Capital toolbox
Second Avenue $50M. Paid off 9 June, about $19.7M. Extinguishment loss $3.2M.
Cap $100M. Issued $8.25M. Undrawn $91.75M is the investors’ option.
Cap up to about $98.1M. H1 net used about $15.4M.
$0.31 / share, about $3.6M, from the shoe proceeds.
Disclosed net cash on the two draws is about $7.3M. Financing-line proceeds are $7.838M. Fair value at 30 June is $8.187M.
Chapter 3 · 3.2 How to read the facility
Face $8.25M. Disclosed net cash about $7.3M. Coupon 12%, in stock or in cash at the company’s option. OID 5%. Issuance costs about $0.5M, expensed at once. Senior lien on all assets, including the AI infrastructure. A lower price issues more shares for the same principal. The filings do not show that loop has been run.
Chapter 3 · 3.3 What was leased · Note 11
April marketing said about $2.75M over three years. Total payments including the option are about $3.7M. Do not invent B200 or B300 counts, megawatts, or tokens per second.
Chapter 3 · 3.3 Cash schedule · $ thousands · 30 June
Total 3,496 − unearned interest 832 = NIL 2,664.
Chapter 3 · 3.3 Concentration · Note 7
100% of continuing revenue. Consideration ~$2.75–3.7M. Term 36 months. No large prepay stressed. Sales-type. Subsidiary legal name, guaranty, SLA, and hall are unfiled.
Thinking Machines path $472M. Other singles $200M+. Often 36–48 months. A construction prepay near 25% is common. The body is an operating lease. Not the same shape.
Any collection problem punches through the AI narrative. BIRD’s own office ROU of $2.502M is a lessee cost, unrelated to the GPU lessor position.
Chapter 3 · 3.4 Continuing P&L · Q2'26 · $ thousands
H1 revenue is the same $2,758. Continuing net loss is $(12,778) in the quarter and $(18,869) in the half. The $1,458 interest-expense line is not the cash coupon. Do not ×4 the revenue.
Chapter 3 · 3.4 Unearned interest
The 10-Q does not disclose the implicit rate. A level annuity near 18.6% is the wrong contract. Payments are about $0.1M a month, then about $0.2M, and fewer than 36 months remained on 30 June.
Chapter 3 · 3.4 · $ thousands
Cash interest paid in the half is zero. A cash hold-to-maturity on about $7.3M of proceeds is roughly 19% nominal, in the same band as the lease yield. Conversion is the path the note is built for. Do not subtract 1,458 from 79 and call the gap the spread.
Chapter 3 · 3.4 Balance sheet · 30 June · $ thousands
Cash and restricted cash move from $27,552 to $38,588. Shoes +$38.2M. Discontinued financing −$25.2M. Continuing financing +$23.4M. GPUs −$2.8M. Operating cash −$7.3M continuing and −$15.9M discontinued. The dividend, about $3.6M, was declared after quarter-end. Further draws are the holders’ option.
Chapter 3 · 3.4 Contract arithmetic only
Bars are the excess over 1.00×, not dollars. BIRD day-one revenue / cost is ~1.0× and is not profit. Q2 interest / NIL is not a full-quarter run-rate. SG&A / NIL is $10.7M / $2.7M. GPU count stays unfiled. BRUN’s $472M path is an anchor, not an isomorphism. Market cap ~$22–30M is a secondary source only.
Chapter 04
A finance-lease neighbor that leases the cards in, then leases them out.
Chapter 4 · 4.1 Lineage · IFRS foreign private issuer
Immuno-oncology. Filings through about Sep 2025.
TON / Telegram. Kaiser becomes CEO 2 August.
Nasdaq Capital Market. Ticker ALP.
From Animoca. A parallel line, not an SPV.
Most executives are independent contractors, with cash plus TON-token bonuses. That is a light shell, not BRUN’s operating team. Villani is also CIO. Mitin speaks on ALPHA-01.
Chapter 4 · 4.2 ALPHA-01 · 6-K and 20-F/A Note 21
Upstream lessor. 504 B200. About $29.6M / 24 months. Deposit $2.6M.
Intermediary. Calls the outbound side finance or sales-type. Spread, not ownership.
Downstream lessee. Exclusive access to an identified cluster. Canada, 100% hydro.
Colo operator unfiled. Who runs the cluster is fuzzier than BIRD’s “lessee operates.”
TCV $32,200,000. Management ARR $16,100,000. Go-live May 2026. Marketed prepay $7.5M. Actual May prepay on the July memo: $6,445,958. Both terms are about 24 months.
Chapter 4 · 4.2 Classification
FYE 31 March 2026. IFRS 15, stand-ready, over time. Revenue $97k is March compute, before ALPHA-01. No NIL line. No finance-versus-operating checklist.
Identified GPU cluster. Lease, not a service. If finance or sales-type, collections split into NIL recovery and finance income. Not filed as a 6-K.
July, unaudited: finance income $465,076, lease interest expense $270,318, cash in $1,084,074, cash out $1,250,928, net cash $(166,854). Do not ×12 the income. Interest expense fits a lessee-sublessor. The $6.45M prepay is described as a two-year monthly credit.
Chapter 4 · 4.2 Statutory book · Form 20-F
Two lessor classes: finance and operating. No sales-type class. A sublease is classified on the right-of-use asset, IFRS 16.B58, not on the GPU. This is the filed framework.
The monthly names ASC 842 beside IFRS 16 and says finance or sales-type. ASC 842 has three lessor classes and classifies a sublease on the GPU. BIRD’s 10-Q is that book.
No U.S. GAAP primary statements. The monthly was not a 6-K. FY2026 policy is still IFRS 15 for $97k of March compute, before ALPHA-01. The paired label is not a second audited test.
Chapter 4 · 4.2 What can leave the balance sheet
Buzz, 24 months. ALP records a right of use and a lease liability. The 504 cards are not PPE.
Outbound term about 24 months. Classify the right of use. Major-part-of-life is an indicator. The dates are not paired in the filing.
Right of use off. Net investment on. Head-lease liability stays. No gross hardware revenue.
No audited NIL. No day-1 gain in the filings. May $26.6M and June $34.4M are lessee liabilities.
Those liabilities are not Buzz’s $29.6M of undiscounted payments. IFRS 16.65: the life example is not always conclusive. A manufacturer or dealer would print selling revenue. ALP has not presented itself as one.
Chapter 4 · 4.2 July 2026 · company monthly, not a 6-K
One dollar scale, cash out at the top. $465,076 minus $270,318 is $194,758, arithmetic, not a disclosed margin. Net cash $(166,854). The company ties that gap to the $6,445,958 May prepayment, a two-year monthly credit. Do not ×12 the income.
Chapter 4 · 4.3 ALPHA-02 · 20-F controls
Cluster 2 revenue of $19.92M in the September deck is a projection, not a booked sales-type lease. July talks only about Alpha-01. Pennsylvania 200 MW is an option term sheet, greenfield, nothing operating. The 5 June “576 B200” loses to the 20-F B300.
Chapter 4 · 4.4 GAMEE runs beside it
GPU offtake. Live May 2026. July engine is lease finance income, $465,076, plus cash collections. A lease, not a purchase price.
60% of GaMee Global, 27 May, implied $18M. Initial ~$3.5M. July revenue $489,000, EBITDA $57,000. 2025 narrative $3.5M. Q1'26 $926k.
Majority-owned games subsidiary. It keeps diluting a “pure GPU lessor.” July still shows both.
Chapter 4 · 4.5 Audited 31 March 2026 · $ thousands
Equipment deposits 9,308. Put-right liability 7,105. Auditor: going-concern substantial doubt. A later narrative, through 13 July, puts cash and restricted cash near $10.3M. GAMEE and ALPHA-01 are both outside FY2026 revenue.
Chapter 4 · 4.5 After year-end · unaudited
21 May: cash $10.2M, assets $66.9M, GPU lease liability $26.6M. 4 June: assets $79.2M, liabilities $44.4M including $34.4M of GPU + data-center leases, equity $34.8M, run-rate $23M.
Not a lessor residual and not an NIL. The 1-for-50 split, effective 9 September, takes the count from about 77.49M to ~1.55M. Grace on the bid runs to 1 March 2027. A split does not create a sales-type note.
July finance income and the prepay memo remain a company PR. CUSIP G7185A144. Still Capital Market ALP.
Chapter 4 · 4.5 Contract arithmetic · not a disclosed IRR
$32.2M − $29.6M = $2.6M over 24 months, about $108k a month, before colo, power, and opex. Prepay coverage about 20% of TCV, below the marketed $7.5M. July financing spread about $195k. July cash −$167k, which the company ties to prepay amortization. Residual, SLA, and Buzz sublease terms are not fully disclosed. Versus BIRD, 1.09× against 1.32×.
Chapter 4 · 4.6 Close
Finance / sales-type in the company’s words. Not operating. Not pure IFRS 15 for ALPHA-01.
Buzz in, lab out, plus GAMEE. Not purchased cards.
Classification is a monthly that was not a 6-K. No audited NIL.
504 cards and $32.2M TCV. Unnamed customer. Spread about 1.09×.
Chapter 05
This chapter is only the income line each book may print.
Chapter 5 · Income line only · pooled compute is the contrast
| IFRS 15 pool | BIRD sales-type | ALP sublease | |
|---|---|---|---|
| Role | Service, if no identified server | Bought the servers | Leased 504 in, then out |
| Day 1 | No hardware revenue | Revenue = cost, $2.758M | No disclosed hardware revenue. Liability stays |
| Later | The fee, as revenue | Interest income, Q2 $79k | Finance income, July $465,076 |
| Cash | Often close to the fee | Principal reduces the NIL | Cash in $1,084,074 is not that income |
$32.2M and $16.1M are contract figures. Audited FY2026 revenue is $97k. The $1,573,074 line adds Gamee revenue to Alpha-01 cash receipts. $194,758 is arithmetic on the two July income lines. The monthly was not a 6-K.